
How Blockchain Technology Works: A Complete Guide
Blockchain technology has become an important innovation in the digital world, transforming how information can be recorded, verified, and shared across computer networks. From cryptocurrencies to supply chain management, blockchain systems offer new approaches to maintaining digital records. However, many beginners find the technology difficult to understand because of its technical terminology. Learning how blockchain technology works can make these concepts easier to understand.
Unlike traditional databases controlled by a single administrator, many blockchain networks distribute recordkeeping responsibilities among multiple computers. These computers follow agreed rules to validate transactions and maintain a shared history of information. Cryptographic techniques help protect records against unauthorized modification. This combination of distributed verification and connected records is a defining feature of blockchain technology.
Understanding blockchain does not require advanced programming skills or extensive technical experience. By exploring transactions, blocks, cryptographic hashes, and consensus mechanisms, beginners can develop a clear understanding of the system. Blockchain also supports applications beyond digital currencies, including automated agreements and shared business records. This guide explains its working process, important components, advantages, limitations, and practical uses.
What Is Blockchain Technology in Simple Words?
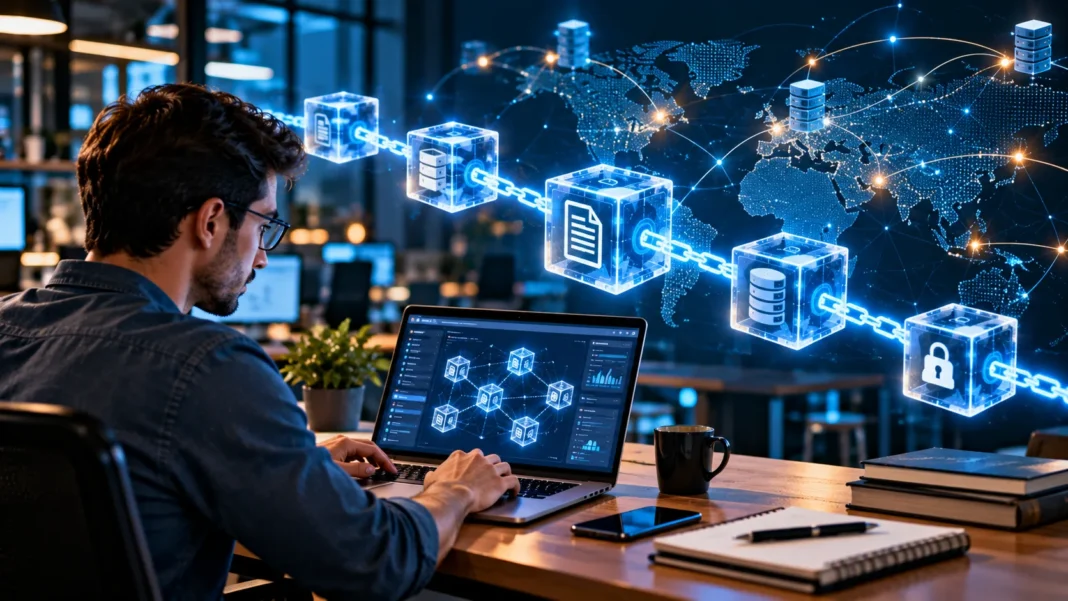
Blockchain technology is a digital recordkeeping system that stores information in groups called blocks. These blocks are connected through cryptographic references, creating a chronological chain of records. Each new block contains information linking it to earlier entries. This structure helps make unauthorized changes to recorded information easier to detect.
Many blockchain networks maintain copies of the ledger across several participating computers. These participants follow specific rules for validating and accepting new transactions. Instead of depending entirely on one organization to maintain records, responsibility can be distributed across the network. However, the degree of decentralization varies between blockchain systems.
Blockchain is commonly associated with Bitcoin and other cryptocurrencies, but its applications extend beyond financial transactions. Businesses may use blockchain-based systems to coordinate information, verify records, or manage digital assets. The technology is particularly relevant when several parties need a shared transaction history. Understanding its basic structure provides a foundation for exploring more advanced applications.
Understanding the Basic Structure of a Blockchain
A blockchain consists of connected blocks containing records and supporting technical information. Each block normally includes transaction data and a cryptographic reference to the preceding block. This reference links the blocks into an ordered sequence. The resulting structure allows participants to examine the history of accepted records.
The information stored inside a block depends on the blockchain network and its purpose. Financial blockchains commonly record transactions involving digital assets. Other blockchain applications may record instructions, document references, or changes to shared systems. Each network defines the types of information that participants can submit.
The chain structure helps preserve consistency between historical records. If information inside an earlier block changes, its cryptographic relationship with subsequent blocks may no longer match. Network verification rules help participants identify such inconsistencies. However, resistance to modification depends on the complete system, including its consensus mechanism and network security.
How a Blockchain Transaction Begins
A blockchain transaction begins when a participant creates an instruction that follows the network’s supported transaction format. In cryptocurrency systems, this might represent a transfer of digital assets between addresses. Other applications may involve smart contract interactions or record updates. The transaction contains information required for the network to evaluate the requested action.
Many blockchain transactions use digital signatures to demonstrate authorization. A participant signs transaction data using a private cryptographic key associated with the relevant account. Network participants can verify the signature using corresponding public information. This process helps establish that an authorized key approved the transaction.
After creation, the transaction is submitted to the blockchain network. Participating computers receive the information and evaluate it according to protocol rules. Invalid transactions may be rejected before becoming part of the ledger. Valid transactions can proceed toward inclusion in a block through the network’s established process.
How Blockchain Networks Verify Transactions
Transaction verification is an important part of maintaining reliable blockchain records. Participating computers check whether submitted transactions follow the network’s rules. These checks may involve digital signatures, available balances, transaction formatting, and other protocol requirements. Verification helps prevent unauthorized or invalid updates from being accepted.
Different blockchains use different methods for determining transaction validity. For example, a cryptocurrency network may reject an attempt to spend assets that are not available under its ledger rules. Smart contract networks may also evaluate instructions against programmed conditions. These checks support consistency across participating computers.
Verification does not mean that every real-world claim associated with a transaction is accurate. A blockchain can confirm that a transaction followed its rules without independently proving the legitimacy of an external business arrangement. This distinction is important when evaluating practical applications. Blockchain security depends partly on the reliability of information entering the system.
How Transactions Are Added to a Block
After transactions pass preliminary checks, eligible transactions can be selected for inclusion in a new block. The exact selection process depends on the blockchain’s design. Some networks prioritize transactions according to fees or other protocol rules. The selected records are organized into a structure suitable for network verification.
A proposed block typically includes transaction information and technical data required by the protocol. These details may include a reference to the previous block and information used by the consensus mechanism. The block must satisfy the network’s validation requirements. Other participating computers can then evaluate whether it should be accepted.
When a proposed block meets the applicable rules, the network may add it to the accepted chain. The ledger is updated to reflect the included transactions. Additional blocks can strengthen confidence that earlier transactions will remain part of the accepted history. However, the level of finality depends on the network’s consensus design.
What Are Cryptographic Hashes in Blockchain?
A cryptographic hash is a mathematical output generated from digital information using a hash function. Blockchain systems use hashes to help connect records and detect changes. A small modification to the original input will generally produce a substantially different output. This characteristic makes hashes useful for checking data integrity.
Each block typically includes a reference derived from information associated with the previous block. These references create connections across the blockchain’s history. If earlier data is altered, the expected relationship between blocks may become inconsistent. Network participants can use these differences to detect certain unauthorized modifications.
Cryptographic hashing does not automatically encrypt or conceal information. Public blockchain transactions may remain visible even though hashes are used to protect their integrity. Hash functions and encryption serve different technical purposes. Understanding this distinction helps explain why blockchain records can be transparent while still benefiting from cryptographic protection.
Understanding Public and Private Keys in Blockchain
Public-key cryptography plays an important role in authorizing many blockchain transactions. A participant controls a private key that can generate digital signatures. Related public information allows other participants to verify those signatures. This arrangement supports transaction authorization without revealing the private key.
A public key or derived address can be used as an identifier within certain blockchain systems. Other participants may use this information to direct transactions toward an account. However, an address is not necessarily the same as a person’s real-world identity. Different networks use different account structures and cryptographic methods.
Private keys require careful protection because they may control valuable digital assets or important account permissions. Anyone who obtains an active private key may be able to authorize transactions within its scope. Blockchain networks generally cannot distinguish an authorized owner from another person using a compromised key. Strong security practices are therefore essential for systems relying on cryptographic credentials.
What Is Blockchain Consensus and Why Is It Important?
Consensus describes the process through which a blockchain network establishes an agreed transaction history. Multiple computers may receive proposed updates at different times. Without coordination, participants could develop conflicting versions of the ledger. Consensus mechanisms provide rules for deciding which updates belong in the accepted record.
The consensus method influences how a blockchain balances security, performance, and decentralization. Some networks rely on computational work, while others use validators operating under economic or permission-based rules. Each approach creates different incentives and technical requirements. Understanding consensus is essential for evaluating blockchain reliability.
A strong consensus mechanism helps reduce the possibility of conflicting or unauthorized ledger updates. However, no consensus system is automatically immune to every attack or operational failure. Network participation, software quality, and governance also affect security. The effectiveness of blockchain verification depends on how these components function together.
How Proof of Work Blockchain Technology Works
Proof of Work is a consensus mechanism used by Bitcoin and certain other blockchain networks. Participants called miners perform computational work while attempting to produce valid blocks. The process requires finding an output that satisfies the network’s difficulty requirements. This work helps make certain forms of ledger manipulation expensive.
When a miner produces a valid block, other network participants can verify it against established rules. The accepted chain represents the transaction history supported by the relevant consensus process. The network adjusts its operating rules according to its protocol. This arrangement allows participants to coordinate without relying on one central recordkeeper.
Proof of Work provides important security properties but also involves tradeoffs. Mining requires computing equipment and electricity, and the total energy consumption can be substantial. Network security also depends on the distribution of mining power. These considerations influence how Proof of Work systems are evaluated and compared with alternative approaches.
How Proof of Stake Blockchain Technology Works
Proof of Stake is another consensus approach used by blockchain networks, including Ethereum. Instead of relying primarily on competitive computational mining, it uses eligible validators operating under staking requirements. Validators participate in proposing or confirming network updates. Their responsibilities and rewards depend on the protocol’s rules.
Staking generally involves committing digital assets under network-defined conditions. Validators may face penalties when they violate certain rules, providing an economic incentive for honest participation. The network uses its consensus process to determine accepted blocks and transaction history. Different Proof of Stake systems implement these principles in different ways.
Proof of Stake can reduce the energy requirements associated with competitive mining. However, it introduces separate concerns involving validator concentration, governance, and protocol security. Its effectiveness depends on careful design and network participation. Understanding these tradeoffs helps explain why blockchain platforms choose different consensus mechanisms.
How Blockchain Prevents Double Spending
Double spending refers to an attempt to use the same digital asset value in conflicting transactions. In digital financial systems, preventing this problem is essential for maintaining trustworthy records. Blockchain networks establish rules for tracking accepted transactions and determining available balances or unspent outputs. These rules help identify conflicting attempts.
Consensus mechanisms allow participating computers to agree on which transaction history is accepted. If conflicting transactions appear, the network applies its validation and ordering rules. Transactions that violate the accepted ledger state are rejected. This process helps maintain consistency across participating computers.
The effectiveness of double-spending prevention depends on network security and transaction finality. Some blockchains provide stronger settlement assurances after additional blocks, while others use different finality mechanisms. Short-term reversals may still be possible under particular circumstances. Understanding these limitations is important when evaluating digital payment systems.
What Are Smart Contracts and How Do They Work?
Smart contracts are programs deployed on blockchain networks that support programmable transactions. They execute predefined instructions when valid interactions satisfy their programmed conditions. These programs can manage digital assets, update records, or coordinate certain activities. Their execution follows the rules established by the supporting blockchain platform.
For example, a smart contract might record a digital ownership transfer when predefined requirements are fulfilled. The blockchain can preserve the resulting transaction history according to its protocol. However, smart contracts cannot automatically verify every real-world event. External data may require additional systems, sometimes called oracles.
Smart contracts introduce both opportunities and technical risks. Programming errors can create unexpected outcomes or expose assets to unauthorized activity. Some deployed contracts are difficult to modify, depending on their design. Thorough review and appropriate security practices are important because automated execution does not guarantee correct or legally enforceable results.
How Blockchain Technology Supports Decentralization
Decentralization involves distributing certain system responsibilities across multiple participants. In blockchain networks, these responsibilities may include record storage, transaction verification, or protocol governance. Distribution can reduce dependence on a single operator for maintaining the ledger. However, not every blockchain distributes control equally.
Public blockchains commonly allow broad participation under published protocol rules. Permissioned systems may restrict validation responsibilities to selected organizations. Both approaches can use blockchain structures, but their trust assumptions differ. Understanding who controls important decisions helps evaluate how decentralized a particular network actually is.
Decentralization can improve resilience under certain conditions, but it may also increase coordination challenges. Decisions about technical upgrades and operating rules can become complicated when many participants are involved. Centralized systems may offer simpler administration for some applications. The appropriate balance depends on security, accountability, and operational requirements.
How Blockchain Technology Works With Cryptocurrency
Cryptocurrencies use blockchain or related distributed ledger systems to maintain records of digital asset activity. Bitcoin is one of the best-known examples. Its blockchain records accepted transactions and establishes rules for transferring value between addresses. These records are maintained through a network of participating computers.
Different cryptocurrency networks use different transaction models and consensus mechanisms. Some support basic transfers, while others include programmable smart contract functionality. Network fees and processing capacity also vary. Understanding these technical differences is important because cryptocurrencies do not all operate identically.
Blockchain technology should not be confused with cryptocurrency investing. The ability to maintain a distributed ledger does not guarantee that a digital asset will increase in value. Cryptocurrency markets involve volatility, fraud risks, and regulatory uncertainty. Learning how the technology works is possible without purchasing or trading digital assets.
Real-World Applications of Blockchain Technology
Blockchain technology has potential applications beyond digital currencies. Businesses have explored shared ledgers for supply chain records, document verification, and coordination between organizations. These systems may help different parties access a consistent history of recorded events. Their usefulness depends on accurate information and appropriate governance.
Financial institutions have also investigated blockchain-based systems for settlement, recordkeeping, and the representation of assets in digital form. Certain applications may simplify coordination between participating organizations. However, implementation requires consideration of regulation, privacy, technical integration, and processing efficiency. Conventional financial infrastructure remains important in many settings.
Other possible applications include digital identity systems and automated business processes. Blockchain records may help establish that particular information existed or was authorized at a given time. Nevertheless, connecting digital information to physical assets or real-world identities remains challenging. Practical value depends on solving specific problems more effectively than available alternatives.
Benefits of Blockchain Technology for Businesses
One potential benefit of blockchain is maintaining consistent records between organizations that operate independently. Shared ledger systems can reduce disagreements about which information has been recorded. Authorized participants may review transaction histories according to established permissions. This transparency can support accountability when the underlying information is reliable.
Blockchain systems can also provide protections against certain forms of unauthorized record modification. Cryptographic links and consensus rules help maintain ledger integrity. These features may be useful for auditing and tracking historical changes. However, they do not eliminate errors, fraud, or security problems elsewhere in a business process.
Automation represents another possible advantage in suitable applications. Smart contracts may reduce some manual verification or administrative activities. Yet blockchain systems can introduce additional operational expenses and technical complexity. Organizations should evaluate whether the benefits justify the implementation costs before adopting distributed ledger technology.
Challenges and Limitations of Blockchain Technology
Blockchain technology faces challenges involving scalability, performance, and operating costs. Some networks process transactions more slowly than centralized systems because updates require coordination between participants. Transaction fees may also fluctuate depending on network activity. These factors can affect suitability for applications requiring high processing volumes.
Privacy and regulatory compliance create additional challenges. Public blockchain records may expose transaction information that organizations would prefer to keep confidential. Permissioned systems offer different access controls but introduce their own governance requirements. Businesses must also consider legal responsibilities when handling sensitive information.
Technical complexity can make blockchain integration difficult for organizations using established software systems. Developers must understand network behavior, security requirements, and maintenance obligations. Smart contract vulnerabilities and incorrect configuration can create serious problems. Successful implementation therefore requires careful planning rather than assuming blockchain automatically improves every process.
How Blockchain Technology May Evolve in the Future
The future of blockchain will depend on practical adoption, technical progress, and regulatory developments. Developers continue exploring ways to improve transaction processing, interoperability, and network efficiency. Businesses are also evaluating applications involving digital records and asset representation. However, widespread adoption will depend on whether these systems deliver measurable benefits.
Interoperability is an important research area because different blockchain networks often operate independently. Improved communication between systems could support more coordinated applications. At the same time, connecting networks may introduce additional security risks. Effective solutions must balance convenience with reliable verification and accountability.
Blockchain may also interact with technologies such as artificial intelligence and connected devices. Some applications could use blockchain records to document data exchanges or automated actions. Nevertheless, combining technologies does not automatically create a useful product. Long-term success will depend on solving real problems with appropriate security and economic efficiency.
Conclusion
Understanding how blockchain technology works begins with learning how transactions, blocks, cryptographic hashes, and consensus mechanisms connect. These components allow participating computers to maintain an agreed history of digital records. Different blockchain networks use different rules and governance structures. The technology offers a distinctive approach to coordinating information without always relying on one administrator.
Blockchain applications extend beyond cryptocurrency into business recordkeeping, automated agreements, and digital verification. Potential benefits include shared transparency, improved data integrity, and reduced administrative duplication. However, technical complexity, privacy concerns, and scalability limitations remain important challenges. The technology is most useful when its advantages address a genuine operational need.
For beginners, learning blockchain concepts provides a foundation for understanding modern distributed systems. Exploring network structure, transaction validation, and smart contracts makes advanced subjects easier to approach. Critical thinking is important because blockchain is not a universal solution. Its long-term value will depend on responsible development, practical applications, and reliable performance.
Frequently Asked Questions (FAQs)
How Does Blockchain Technology Work in Simple Terms?
Blockchain records validated transactions in connected blocks that form a shared ledger. Participating computers follow agreed rules to verify updates, while cryptographic techniques help detect unauthorized changes to stored information.
What Are the Main Components of Blockchain Technology?
Important components include transactions, blocks, cryptographic hashes, digital signatures, network participants, and consensus mechanisms. Together, these elements help organize records and establish an accepted transaction history.
Why Is Blockchain Considered Secure?
Blockchain can resist unauthorized record changes through cryptographic linking and distributed verification. However, security depends on network design, software quality, user credentials, and protection against potential attacks.
Is Blockchain Technology Only Used for Bitcoin?
No, Bitcoin is one application of blockchain technology. Other systems explore uses involving smart contracts, shared business records, supply chains, digital verification, and financial infrastructure.
Can Blockchain Technology Be Hacked?
Blockchain-related systems can experience security breaches through software vulnerabilities, compromised credentials, smart contract errors, or network attacks. The risks vary depending on the blockchain’s architecture and implementation.