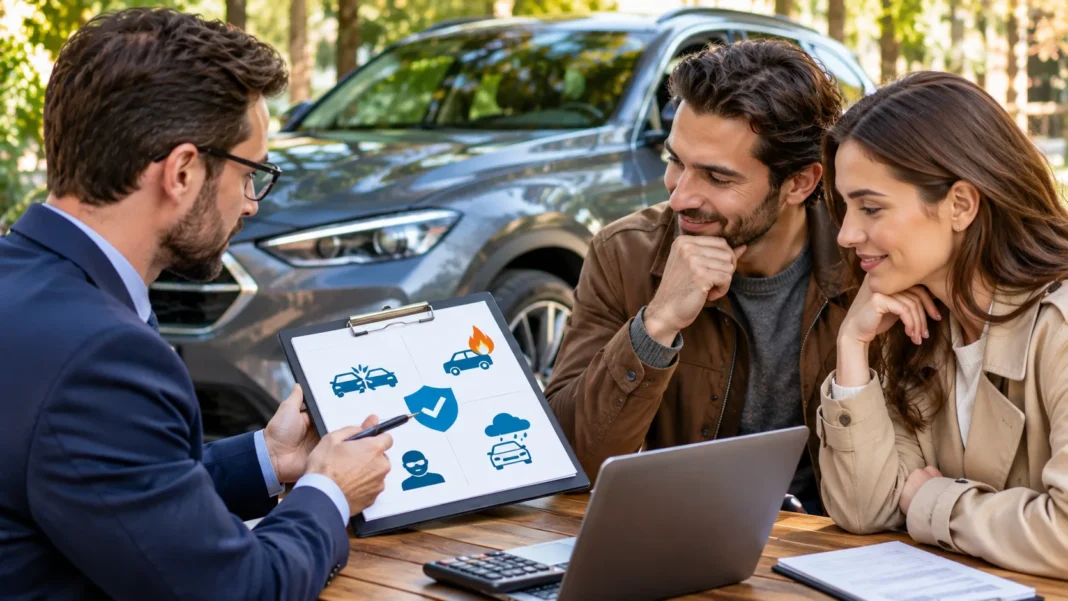

Car insurance protects drivers from unexpected financial expenses caused by accidents, theft, and vehicle damage. However, choosing the right insurance policy can become confusing when companies use terms like liability, collision, comprehensive, and full coverage insurance. Many drivers believe full coverage means their insurance company will pay for every possible loss, but that is not necessarily true.
Full coverage insurance is commonly used to describe a combination of different auto insurance protections. It typically includes liability insurance, collision coverage, and comprehensive coverage. These policies work together to help pay for damage to your vehicle and certain expenses involving other people.
Understanding what full coverage insurance includes can help you choose appropriate protection without paying for unnecessary features. This guide explains how full coverage car insurance works, what it covers, what it excludes, and how much it may cost. You will also learn how to compare policies, select deductibles, and determine whether full coverage is right for your vehicle.
What Is Full Coverage Insurance?
Full coverage insurance is a common term used to describe an auto insurance policy that combines several types of protection. It usually includes liability, collision, and comprehensive insurance. Together, these coverages help pay for certain accident-related expenses and damage to your own vehicle. However, full coverage is not an official insurance policy category with one universal definition.
The term can mean slightly different things depending on the insurance provider, state, and individual policy. Some insurers may discuss additional protections, such as uninsured motorist coverage or personal injury protection, when describing broader insurance packages. These extra benefits are not automatically included in every full coverage policy. Drivers should always review the actual coverage details before purchasing.
Full coverage does not mean every possible accident, repair, or financial loss will be covered. Policies contain deductibles, coverage limits, exclusions, and specific conditions. Understanding these restrictions is essential because they determine what an insurance company will pay after a claim. Reading policy documents carefully helps prevent unexpected expenses.
What Does Full Coverage Car Insurance Include?
Full coverage car insurance generally combines three main protections: liability, collision, and comprehensive coverage. Liability insurance helps pay for certain injuries or property damage you cause to others. Collision insurance helps repair or replace your vehicle after covered accidents. Comprehensive insurance covers many types of vehicle damage unrelated to collisions.
These protections address different financial risks associated with owning and driving a vehicle. For example, liability insurance may pay for damage to another driver’s car when you cause an accident. Collision coverage may help repair your own vehicle after the same incident. Each coverage applies according to its specific terms and limits.
Additional insurance options may be available depending on state laws and individual needs. These include medical payments coverage, personal injury protection, uninsured motorist insurance, and rental reimbursement. Some protections are mandatory in certain states, while others remain optional. Always check your policy declarations page to understand exactly which coverages you have purchased.
Liability Insurance: Protection When You Cause an Accident
Liability insurance is a fundamental component of most auto insurance policies. It helps pay for covered injuries and property damage suffered by other people when you are legally responsible for an accident. Most U.S. states require drivers to carry minimum liability insurance. However, minimum requirements vary depending on the state.
Bodily injury liability coverage helps pay for another person’s medical expenses, lost wages, and certain legal costs following a covered accident. Property damage liability insurance helps pay for repairs to another person’s vehicle, fence, building, or other property. These protections operate within the policy’s coverage limits. Expenses exceeding those limits may become your responsibility.
Liability insurance generally does not pay to repair your own vehicle after an accident you cause. It also does not automatically cover your personal medical expenses. This is one reason drivers consider additional auto insurance protections. Selecting suitable liability limits is important because serious accidents can create substantial financial obligations.
Collision Coverage: Protection for Your Vehicle
Collision insurance helps pay for damage to your own vehicle following certain accidents. It typically applies when your car collides with another vehicle or an object such as a tree, fence, or guardrail. Coverage may also apply when your vehicle overturns. These protections are subject to the policy’s terms and deductible.
For example, suppose you accidentally hit a parked vehicle while driving. Your property damage liability coverage may help pay for the other vehicle’s damage. Collision insurance may help cover repairs to your own car. This combination provides broader financial protection than carrying liability coverage alone.
Collision coverage is generally optional under state insurance laws, but lenders frequently require it for financed or leased vehicles. The insurance company usually pays covered repair costs after subtracting your deductible. If the vehicle is declared a total loss, compensation is generally based on its covered value. Policy limits and settlement conditions still apply.
Comprehensive Coverage: Protection Beyond Accidents
Comprehensive insurance helps cover vehicle damage caused by events other than most collisions. Common covered situations include theft, vandalism, fire, hail, falling objects, and certain weather-related damage. It may also cover damage caused by hitting an animal. The exact protection depends on the insurance policy.
Imagine your vehicle is parked outside during a severe storm and falling branches damage its roof. Comprehensive insurance may help pay for repairs after the applicable deductible. Similarly, if your car is stolen, this coverage may provide compensation according to its insured value. These situations are generally not covered by standard collision insurance.
Comprehensive coverage is particularly useful for drivers concerned about theft, severe weather, or unexpected environmental damage. However, it does not cover every mechanical problem or maintenance expense. Insurance companies may also apply special conditions to certain claims. Reviewing exclusions and deductibles helps clarify how this protection works.
Does Full Coverage Insurance Include Medical Expenses?
Full coverage insurance does not automatically include complete medical protection for the driver and passengers. Although liability insurance covers certain injuries suffered by other people, your own medical expenses may require separate coverage. The available options depend on state insurance laws. Understanding these differences is important when comparing policies.
Medical payments coverage, commonly called MedPay, can help pay eligible medical expenses for you and your passengers after a covered accident. Personal injury protection, or PIP, may provide broader benefits, including certain lost wages and related expenses. Coverage details and eligibility vary by state. Some states require particular medical protections.
Uninsured and underinsured motorist coverage may also provide protection when another driver lacks sufficient insurance. Depending on the policy and state, it can help cover eligible injuries or property losses. These protections are not automatically included in every package described as full coverage. Check your policy documents before assuming medical expenses are covered.
What Does Full Coverage Insurance Not Cover?
Despite its name, full coverage insurance does not provide unlimited protection against every vehicle-related expense. Standard policies generally exclude routine maintenance, normal wear and tear, and mechanical breakdowns unrelated to covered events. Expenses involving oil changes, tire replacement, and regular servicing usually remain the owner’s responsibility. Separate service contracts may cover certain mechanical repairs.
Another important limitation involves the difference between a vehicle’s insured value and its outstanding loan balance. If your car is declared a total loss, the insurance settlement may be lower than what you still owe. Standard collision or comprehensive coverage generally does not pay that difference. Guaranteed asset protection, commonly called gap insurance, may address certain shortfalls.
Other exclusions may involve unauthorized drivers, commercial activities, intentional damage, or particular uses of the vehicle. For example, personal auto insurance may not cover some rideshare or delivery activities without appropriate coverage. Policies also contain limits on covered expenses. Understanding exclusions before an accident helps prevent unexpected claim denials.
Full Coverage vs. Liability Insurance: Key Differences
The biggest difference between full coverage and liability-only insurance is the protection available for your own vehicle. Liability insurance primarily addresses covered injuries and property damage caused to others. Full coverage usually adds collision and comprehensive insurance. These additional protections help cover many types of damage to the insured vehicle.
Liability-only insurance generally costs less because it provides fewer types of protection. However, drivers without collision or comprehensive coverage may need to pay for repairs to their own vehicles after certain incidents. The financial consequences can be significant when repairs are expensive. Choosing coverage involves balancing insurance premiums against potential personal expenses.
Full coverage is often more suitable for newer, valuable, financed, or leased vehicles. Liability-only insurance may be worth considering for older vehicles with relatively low market values, provided financing requirements allow it. However, personal savings and risk tolerance also matter. The most appropriate policy depends on your financial circumstances and protection needs.
How Much Does Full Coverage Insurance Cost?
The cost of full coverage car insurance varies widely between drivers, vehicles, locations, and insurance companies. Premiums depend on several factors, including driving history, vehicle type, annual mileage, and selected coverage limits. Insurers may also consider location-based claim patterns and repair costs. State regulations influence which pricing factors companies can use.
A driver with a newer vehicle may pay more for physical damage coverage because repairs or replacement can be expensive. Similarly, choosing higher liability limits or lower deductibles may increase monthly premiums. Some insurers provide discounts for qualifying safety equipment or multiple insured vehicles. Available discounts and eligibility requirements differ between companies.
There is no single full coverage insurance price suitable for every driver. The most reliable approach is to request personalized quotes from multiple licensed insurers. Compare policies using the same coverage limits and deductibles. This helps identify meaningful price differences without accidentally comparing insurance packages that provide different levels of protection.
How Do Deductibles Work With Full Coverage Insurance?
A deductible is the amount you must pay toward a covered claim before your insurance company pays the remaining eligible amount. Collision and comprehensive insurance commonly include separate deductibles. Liability coverage generally does not work through a standard deductible for covered third-party claims. Understanding these differences makes insurance decisions easier.
Suppose your vehicle experiences $3,000 in covered collision damage and your deductible is $500. Under a typical policy, the insurer would pay $2,500 toward the approved repair cost. You would be responsible for the remaining $500. Actual settlements depend on policy conditions, repair estimates, and any applicable limitations.
Choosing a higher deductible often reduces insurance premiums because you accept more financial responsibility after a claim. A lower deductible generally increases the premium but reduces your out-of-pocket expense for a covered loss. Consider how much you could comfortably pay unexpectedly. Selecting a deductible should reflect both your budget and financial preparedness.
Is Full Coverage Insurance Required by Law?
Most U.S. states require drivers to maintain certain minimum auto insurance protections. These requirements commonly include bodily injury and property damage liability coverage. Some states also require personal injury protection or uninsured motorist coverage. However, state laws generally do not require every driver to purchase collision and comprehensive insurance.
The situation can be different when a vehicle is financed or leased. Banks, credit unions, and leasing companies often require borrowers to maintain collision and comprehensive coverage. These requirements help protect the lender’s financial interest in the vehicle. Failure to maintain required coverage may violate the financing agreement.
Drivers who own their vehicles outright usually have more flexibility when choosing collision and comprehensive coverage. They may decide whether the additional protection is worth its cost. However, they must still meet applicable state insurance requirements. Reviewing both legal obligations and financial agreements helps drivers maintain appropriate coverage.
Who Should Consider Full Coverage Car Insurance?
Full coverage car insurance is often worth considering for owners of newer or expensive vehicles. Repairing modern cars can involve costly replacement parts, advanced sensors, and specialized labor. Collision and comprehensive insurance may reduce the financial burden of covered damage. This protection can be especially valuable when vehicle replacement would be difficult.
Drivers with outstanding auto loans or lease agreements commonly need broader protection because of lender requirements. Full coverage may also appeal to individuals who rely heavily on their vehicles for commuting or family responsibilities. However, rental reimbursement is usually a separate coverage. Confirming transportation-related benefits can help avoid disruptions after an accident.
Older vehicles may require a different financial evaluation. If the vehicle’s market value is low, the cost of collision and comprehensive premiums may become difficult to justify. Consider the deductible, potential insurance payout, and your available savings. These factors help determine whether maintaining full coverage makes financial sense.
How to Choose the Right Full Coverage Insurance Policy
Choosing suitable full coverage insurance begins with understanding your vehicle’s value and personal financial situation. Consider how much you could afford to pay after an accident, theft, or major repair. Review your driving habits and local weather conditions. These factors can help identify the types of protection most relevant to you.
Next, compare liability limits, collision deductibles, comprehensive deductibles, and optional benefits across different insurers. A cheaper premium may come with higher deductibles or lower protection limits. Look beyond the monthly price to understand your potential expenses after a claim. Consistent comparison criteria make policy differences easier to recognize.
Customer service, claims procedures, and financial stability are additional considerations when selecting an insurer. Review policy exclusions and ask questions about unclear terms before purchasing. Confirm whether discounts apply and how they affect renewal prices. Taking time to understand the contract supports better long-term insurance decisions.
Conclusion
Full coverage insurance generally refers to an auto insurance package combining liability, collision, and comprehensive protection. These coverages help address different financial risks involving accidents, theft, weather damage, and liability claims. However, full coverage does not mean every possible expense is insured.
Understanding policy limits, deductibles, exclusions, and optional benefits is essential before choosing coverage. Some drivers may need additional protections, such as uninsured motorist insurance, medical payments coverage, or gap insurance. Comparing policies carefully helps identify the differences between available insurance packages.
The right car insurance policy depends on your vehicle, financial situation, state requirements, and personal preferences. Full coverage may provide valuable financial protection, particularly for newer or financed vehicles. Reviewing your insurance needs regularly can help ensure your policy continues to provide appropriate protection.
Frequently Asked Questions
What does full coverage insurance actually cover?
Full coverage insurance typically combines liability, collision, and comprehensive protection. It helps cover certain injuries or damage caused to others, accidents involving your vehicle, theft, vandalism, and covered weather-related damage.
Is full coverage insurance the same as comprehensive insurance?
No, comprehensive insurance is only one part of a typical full coverage package. Comprehensive coverage addresses many non-collision events, while full coverage usually also includes liability and collision insurance.
Does full coverage insurance pay for everything?
No, full coverage insurance has deductibles, coverage limits, and exclusions. Routine maintenance, normal wear and tear, and certain unauthorized or commercial vehicle uses are generally not covered under standard personal auto policies.
Is full coverage insurance required for a financed car?
Most lenders require financed vehicles to carry collision and comprehensive insurance in addition to legally required liability coverage. Specific requirements depend on the loan agreement and applicable state insurance laws.
When should you consider dropping full coverage insurance?
You may consider dropping collision or comprehensive coverage when an older vehicle’s value becomes relatively low compared with the cost of insurance. Evaluate potential payouts, deductibles, savings, and lender requirements before making changes.