
Blockchain technology is a digital system designed to record, verify, and share information across a network of computers. Its main purpose is to create a reliable record of transactions without requiring every participant to depend on one central authority. By combining cryptography, distributed records, and network agreement, blockchain makes certain kinds of information more difficult to change without detection.
Understanding what the purpose of blockchain technology is has become increasingly important as businesses explore new ways to manage digital transactions, financial records, and shared information. Although blockchain is commonly associated with cryptocurrencies such as Bitcoin, its potential applications extend to supply chains, digital identity, and business operations.
What Is Blockchain Technology?
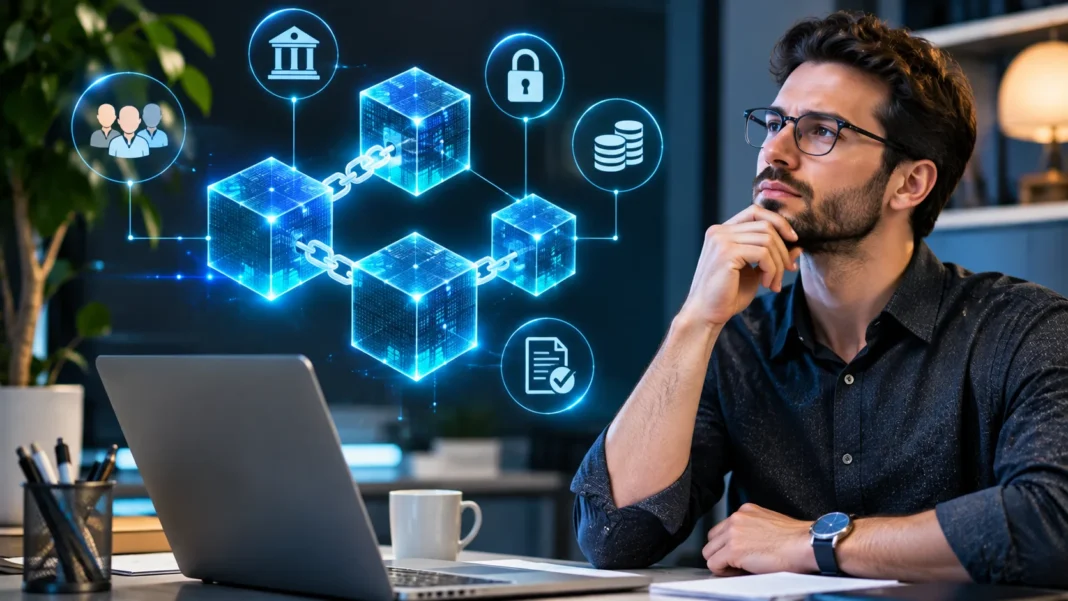
Blockchain technology is a type of distributed digital ledger that records information in groups called blocks. These blocks are connected using cryptographic techniques to create a chronological chain of records. Copies of the ledger are maintained by participating computers within a network. This structure makes the shared history more resistant to unauthorized changes.
Each block typically contains transaction information, a reference to an earlier block, and other technical data. Cryptographic hashes help connect the blocks and reveal certain types of modification. When a block changes, its hash also changes, potentially breaking the relationship with later blocks. Network validation rules help participants recognize which records belong to the accepted history.
Blockchain networks can operate under different governance and access arrangements. Public blockchains generally allow broad participation, while private or permissioned blockchains restrict certain activities to approved participants. These differences affect transparency, performance, security responsibilities, and control. Understanding the network structure is essential when evaluating whether blockchain technology is appropriate for a particular application.
What Is the Main Purpose of Blockchain Technology?
The main purpose of blockchain technology is to maintain a shared, verifiable transaction history among participants who may not fully trust one another. Instead of relying exclusively on a central record keeper, blockchain networks use predefined rules to validate and organize information. This approach helps participants agree on the accepted state of a shared ledger.
Blockchain can reduce certain problems associated with disconnected records and inconsistent transaction histories. When authorized participants access the same ledger, they can compare information against a common source. This may simplify reconciliation and improve the traceability of recorded activities. However, the actual benefits depend on the application’s design and the quality of the information entered.
Another important purpose is to make unauthorized changes to historical records difficult or detectable. Cryptographic connections and consensus mechanisms support the integrity of accepted transactions. These protections do not guarantee that every recorded statement is accurate or that every application is secure. Blockchain provides a technical framework for shared records rather than a universal solution to trust.
How Does Blockchain Technology Work?
Blockchain technology works through a sequence of transaction submission, validation, agreement, and record storage. A participant first submits a transaction or other permitted data to the network. Depending on the blockchain, participating computers check whether the transaction follows established rules. Valid transactions may then be grouped into blocks or processed through another approved recording structure.
The network uses a consensus mechanism to determine which proposed records become part of its accepted history. Different blockchain systems use different methods to achieve agreement. Some rely on computational work, while others use validators operating under economic or permission-based rules. The chosen mechanism affects security, energy requirements, processing speed, and network participation.
After transactions are accepted, participating computers update their copies of the ledger according to the network protocol. Cryptographic references connect new blocks with earlier records and help establish the sequence of events. The resulting history can be verified against the network’s rules. However, confirmation times and the possibility of transaction reversal vary between blockchain systems.
Why Is Decentralization Important in Blockchain?
Decentralization refers to distributing certain responsibilities across multiple participants rather than concentrating them within one organization. In blockchain networks, computers may independently verify transactions and maintain copies of the ledger. This structure can reduce dependence on a single database administrator. However, the degree of decentralization varies significantly between networks.
A decentralized ledger may remain available even when an individual computer experiences a failure. Other participating systems can continue maintaining the accepted records, depending on network conditions. This resilience can be valuable for applications requiring shared access across organizations. Nevertheless, software failures, network disruptions, and concentrated control can still create significant risks.
Decentralization also introduces trade-offs involving performance, governance, and accountability. Reaching agreement among independent participants can require additional communication and processing. Some blockchain networks therefore prioritize efficiency over unrestricted participation. Evaluating decentralization requires understanding who controls validation, software updates, access permissions, and important operational decisions.
How Blockchain Improves Data Transparency
Transparency is one of the commonly discussed purposes of blockchain technology. Public blockchains often allow anyone to inspect transaction records through compatible software or blockchain explorers. This visibility can make certain activities easier to independently verify. However, transparency depends on the network’s design and does not necessarily reveal the real-world identities behind transactions.
Organizations may use shared ledgers to provide authorized participants with consistent information. For example, businesses working together on a supply chain may record selected product movements or transaction milestones. Access to common records can help reduce disagreements about recorded events. The usefulness of this information depends on accurate reporting and appropriate access controls.
Not every blockchain application requires complete public visibility. Permissioned networks may restrict information to approved organizations or individuals. Sensitive business information and personal data often require additional privacy protections. Therefore, transparency should be designed around practical needs rather than treated as a requirement for exposing all recorded information.
The Role of Blockchain in Data Security
Blockchain uses cryptographic techniques to help protect the integrity of its records. Hash functions create compact representations of data, while digital signatures can authenticate authorized transaction instructions. These tools make certain forms of unauthorized modification easier to detect. Network validation adds another layer of protection by checking transactions against established rules.
Security also depends on how the blockchain network is operated and maintained. Weak software, compromised private keys, or poorly designed applications can create serious vulnerabilities. Smart contract errors may expose funds or information even when the underlying blockchain continues functioning correctly. Cryptography alone cannot eliminate every security risk.
Private key management is particularly important in systems where digital signatures authorize transactions. If an unauthorized person gains control of a key, they may be able to perform actions associated with it. Secure storage, access management, software testing, and operational oversight remain necessary. Blockchain security should therefore be understood as a combination of technical controls and responsible administration.
Why Blockchain Records Are Difficult to Change
Blockchain records are often described as immutable, meaning they are intended to resist unauthorized historical modification. Cryptographic hashes connect blocks so that changing earlier data affects the references stored in later blocks. This connection helps participants detect inconsistencies in the ledger. However, immutability is better understood as resistance to modification rather than an absolute guarantee.
The difficulty of changing records also depends on the network’s consensus mechanism. An attacker attempting to rewrite accepted history may need substantial computational resources, control over validators, or other network-specific capabilities. Different systems provide different levels of protection. Smaller or poorly governed networks may be more vulnerable to certain attacks.
Some blockchains can also experience reorganizations, governance interventions, or exceptional software changes. These possibilities demonstrate that historical permanence depends partly on technical and social decisions. Additionally, incorrect information can remain recorded if the system accepts it. Blockchain can preserve records reliably without automatically verifying the truth of every real-world claim.
What Is the Purpose of Blockchain in Cryptocurrency?
Cryptocurrency is one of the best-known applications of blockchain technology. Networks such as Bitcoin use blockchain to maintain a shared history of digital asset transactions. Participants can verify transfers according to publicly defined rules without depending on a traditional bank to maintain the central ledger. This demonstrates how blockchain can coordinate records among independent users.
Blockchain also helps address the double-spending problem in digital currency systems. Digital information can normally be copied, creating challenges when representing transferable value. A cryptocurrency network uses transaction validation and consensus rules to determine which transfers are accepted. This prevents the same units from being validly spent twice within the accepted ledger history.
Cryptocurrencies also introduce financial and technical risks. Prices can fluctuate substantially, transactions may be difficult to reverse, and access can be lost when important credentials are unavailable. Fraudulent services and insecure applications create additional concerns. Understanding blockchain’s role in cryptocurrency does not mean digital assets are automatically safe or suitable for every user.
How Blockchain Supports Financial Transactions
Financial institutions and technology companies have explored blockchain for recording and coordinating certain types of transactions. Potential applications include payment processing, asset transfers, and shared settlement records. A common ledger may reduce the need for repeated reconciliation between participating organizations. However, regulatory obligations and existing financial systems still influence implementation.
Cross-border payments are another area of interest because international transfers can involve multiple intermediaries. Blockchain-based systems may offer alternative arrangements for transmitting transaction instructions or transferring digital assets. Actual speed, costs, and reliability depend on the complete service. Currency conversion, compliance checks, and connections with traditional banking infrastructure remain important considerations.
Financial blockchain applications also face challenges involving privacy, legal responsibility, and operational resilience. Institutions need reliable identity verification, transaction monitoring, and dispute management processes. A technically efficient ledger does not automatically solve these business requirements. Successful implementation depends on integrating blockchain with appropriate financial controls and regulatory frameworks.
The Purpose of Blockchain in Supply Chain Management
Supply chains involve manufacturers, suppliers, transport companies, warehouses, and retailers sharing information across multiple systems. Blockchain may provide a common record of selected transactions and product movements. This can make it easier for authorized participants to review the recorded history of goods. The technology is particularly relevant when several independent organizations need coordinated information.
For example, a food supply chain might record harvesting, processing, shipment, and delivery milestones. Participants could use those records to investigate product movements or verify selected handling events. However, blockchain cannot independently confirm that physical goods match their digital descriptions. Reliable sensors, inspections, and honest data entry remain essential.
Implementing blockchain in supply chains requires agreement on data standards, responsibilities, and access permissions. Participating organizations must decide which information should be recorded and who can verify it. Existing software systems may also need integration. Without these arrangements, a shared ledger can add complexity rather than solve meaningful operational problems.
How Blockchain Is Used in Healthcare
Healthcare organizations manage sensitive records that require accuracy, privacy, and controlled access. Blockchain has been explored as a way to coordinate selected record permissions, verification events, and information-sharing activities. Instead of storing entire medical files directly on a blockchain, some designs record references or evidence of transactions. This can reduce unnecessary exposure of sensitive information.
Potential applications include verifying document integrity and tracking certain pharmaceutical supply chain events. A shared record may help authorized organizations review when specific information was created or updated. However, the system must work alongside existing healthcare software and legal privacy requirements. Reliable medical data management involves more than maintaining a transaction history.
Healthcare blockchain projects face particular challenges because patient information may need correction, restriction, or deletion under applicable laws. Permanent public storage is often unsuitable for confidential records. Access management, interoperability, and cybersecurity remain critical considerations. As a result, blockchain is generally evaluated as a supporting technology rather than a replacement for established medical systems.
Blockchain Technology and Digital Identity
Digital identity systems help individuals and organizations demonstrate selected information about themselves. Traditional systems often depend on databases managed by governments, employers, or commercial service providers. Blockchain has been explored as a way to support verifiable digital credentials. These systems may allow organizations to confirm certain claims without repeatedly contacting the original issuer.
For example, a digital credential could represent a qualification issued by an educational institution. A verification system might use cryptographic evidence connected to a shared registry to check its authenticity. The underlying blockchain does not necessarily need to store personal details. Careful design can help limit unnecessary disclosure while preserving verification capabilities.
Digital identity applications still face significant practical challenges. Lost credentials, identity theft, inaccurate claims, and disputes require reliable recovery and correction procedures. Users also need accessible systems that do not create additional barriers. Blockchain can support selected verification functions, but trustworthy identity management depends on institutions, policies, and secure technology working together.
What Are Smart Contracts in Blockchain?
Smart contracts are programs that operate within compatible blockchain environments. They execute predefined instructions when relevant conditions are satisfied according to the system’s rules. Despite their name, smart contracts are not necessarily legally enforceable contracts. They are software components used to automate specific processes involving digital information or assets.
For example, a smart contract might update a digital record after receiving a valid transaction. It could also apply predefined rules to transactions between participants. This automation may reduce the need for certain manual processing steps. However, the program can only act on information available to it through the blockchain or connected services.
Smart contracts create additional risks because programming errors can affect automated outcomes. Incorrect logic, insecure external connections, and unexpected interactions may lead to financial or operational problems. Publicly deployed programs may also be difficult to modify. Thorough testing, security review, and appropriate governance are essential when smart contracts support important services.
Public vs. Private Blockchain Technology
Public blockchains generally allow broad participation in activities such as viewing records and submitting transactions. Depending on the network, individuals may also participate in transaction validation. These systems often emphasize open access and independent verification. However, their governance structures, processing capacity, and participation rules vary considerably.
Private blockchains restrict certain network activities to approved participants. Businesses may use these systems when they need controlled access, confidentiality, or defined responsibilities. Permissioned networks can also establish specific requirements for validators and data sharing. These arrangements may offer operational advantages while providing less decentralization than some public systems.
Choosing between public and private blockchain technology depends on the application. Open networks may suit systems requiring broad independent participation, while permissioned networks may better match certain organizational requirements. Neither approach is automatically superior. Security, privacy, governance, performance, and cost should guide the decision.
Blockchain vs. Traditional Database Systems
Traditional databases store and organize information through systems that usually operate under defined administrative control. They can support fast searches, frequent updates, and complex business processes. Many organizations already depend on relational and nonrelational databases for everyday operations. These technologies remain effective for a wide range of information management tasks.
Blockchain differs by emphasizing shared validation and a history that is difficult to modify without detection. Instead of relying entirely on one administrator, participating systems may verify records using common rules. This can be useful when multiple organizations require a common transaction history. However, the additional agreement process may introduce performance and operational costs.
A blockchain is not automatically better than a conventional database. If one trusted organization already controls the information and no independent verification is needed, a traditional system may be simpler. Blockchain becomes more relevant when shared governance and resistance to unilateral modification provide meaningful value. Selecting the appropriate technology requires evaluating actual business needs.
Benefits and Limitations of Blockchain Technology
Blockchain offers several potential benefits, including shared records, transaction traceability, and reduced dependence on centralized administrators. Cryptographic verification can help participants detect unauthorized modifications. Certain applications may also simplify coordination between independent organizations. These advantages explain why blockchain continues to attract attention across different industries.
However, blockchain systems can introduce significant limitations. Some networks process transactions more slowly than traditional databases, while others involve substantial operating costs. Privacy, software vulnerabilities, governance disputes, and integration challenges may complicate implementation. Energy requirements also vary depending on the consensus mechanism and network design.
Another limitation is that blockchain cannot automatically guarantee accurate information entering the system. Incorrect records can become difficult to correct once accepted. Organizations must therefore establish reliable procedures for data collection, access, and dispute resolution. Blockchain works best when its specific benefits justify the additional technical and administrative complexity.
The Future Purpose of Blockchain Technology
The future of blockchain technology will likely depend on applications that solve identifiable coordination and verification problems. Organizations continue exploring shared digital records, asset representation, and automated transaction systems. Some projects may become useful infrastructure, while others may prove less practical than existing alternatives. Long-term adoption depends on measurable value rather than technological novelty.
Interoperability is an important consideration because different blockchains and traditional systems often operate separately. Applications may need secure ways to exchange information across networks and established databases. Improvements in software standards and integration could make certain implementations easier to manage. However, technical compatibility alone cannot resolve every legal or governance challenge.
Privacy, security, and regulatory requirements will also influence future development. Businesses and public institutions must evaluate how blockchain systems handle sensitive information, accountability, and operational failures. Effective solutions will require careful design and realistic expectations. The technology’s lasting importance will depend on where it provides clear advantages over simpler approaches.
Conclusion
The primary purpose of blockchain technology is to create a shared, verifiable record of transactions and information across participating systems. It combines cryptographic methods, network validation, and distributed recordkeeping to reduce certain forms of centralized dependence. These characteristics can support transparency, traceability, and data integrity when applied appropriately.
Blockchain applications extend beyond cryptocurrency into finance, supply chains, digital identity, healthcare, and automated business processes. However, every application has different requirements for security, privacy, performance, and governance. The technology does not automatically guarantee accurate information or eliminate operational risks.
Understanding blockchain means recognizing both its practical capabilities and its limitations. In some situations, a shared ledger can solve problems that traditional systems struggle to address. In others, a conventional database may offer a simpler and more efficient solution. The best use of blockchain comes from matching its design to a genuine need.
Frequently Asked Questions (FAQs)
What is the main purpose of blockchain technology?
The main purpose of blockchain technology is to maintain shared, verifiable records across participating computers. It helps establish an agreed transaction history while reducing dependence on a single central record administrator.
Why is blockchain technology important?
Blockchain is important because it offers an alternative method for coordinating and verifying shared information. Its cryptographic and distributed design can support traceability, record integrity, and independent verification in suitable applications.
Is blockchain technology only used for cryptocurrency?
No, blockchain technology has potential applications beyond cryptocurrency, including supply chain tracking, digital identity verification, financial settlement, and selected healthcare processes. Its usefulness depends on the requirements of each application.
What is the difference between blockchain and Bitcoin?
Blockchain is a technology for maintaining shared digital records, while Bitcoin is a cryptocurrency network that uses blockchain. Other blockchain systems can support different assets, applications, and governance arrangements.
Can blockchain technology be hacked?
Blockchain systems can experience security failures through compromised credentials, software vulnerabilities, consensus attacks, or insecure applications. Cryptographic protections make certain attacks difficult, but no blockchain system is completely immune to security risks.